The UK economy has shown a recovery, with a 0.6% growth in the second quarter of 2024, following a 0.7% increase in the first quarter. This growth aligns with economists’ forecasts and marks a continued rebound from the mild recession experienced in the latter half of 2023. The primary driver of this growth has been the services sector, particularly advancements in the IT field, legal services, and scientific research.
However, this recovery is somewhat of an illusion. The growth rate remains below the inflation rate, and the overall GDP output is still around the pre-COVID era levels. This suggests that the economy has not fully recovered from the pandemics impact and that the current growth is not as robust as it appears.
Moreover, the success of this growth cannot be attributed to any specific government action. The new Labour government, which has emphasized economic growth as a central policy objective, has not yet had a significant impact on the economy. The growth observed is largely a result of natural economic cycles and the resilience of the services sector.
In June, economic growth remained stagnant, with no increase in GDP. This was partly due to labour strikes, particularly by junior doctors, and adverse weather conditions that affected retail sales and construction activities. The Bank of England’s recent interest rate cut to 5% is seen as a positive step, but high interest rates continue to pose a challenge to sustained economic growth.
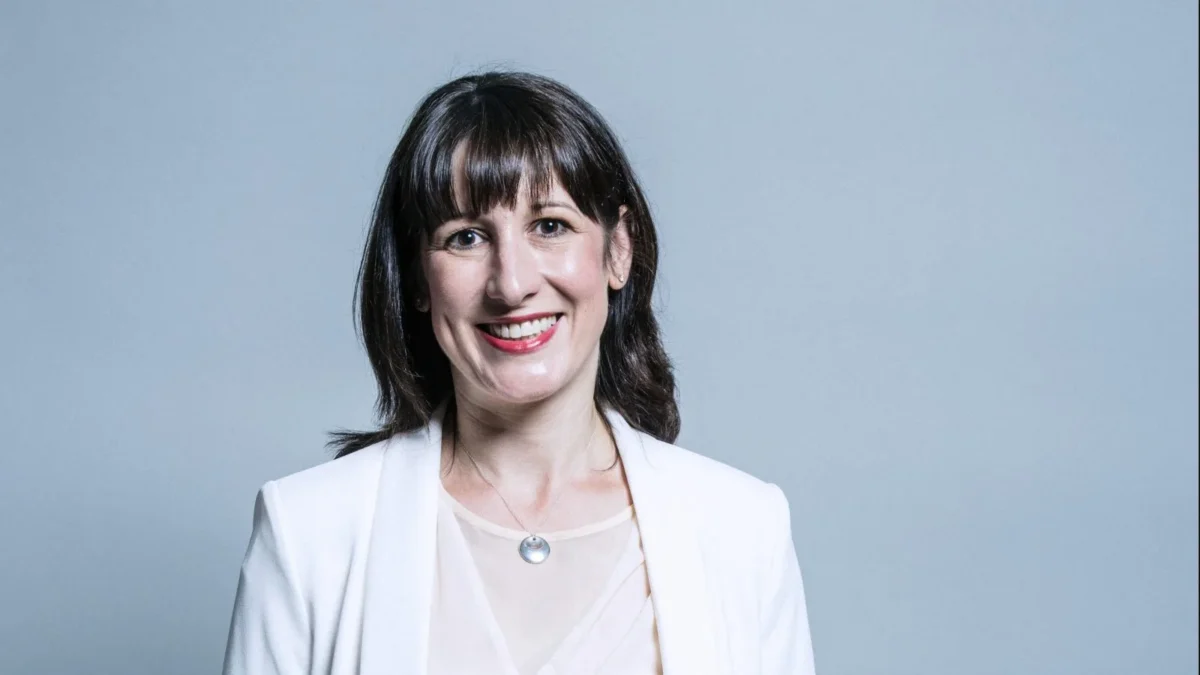
Chancellor Rachel Reeves has acknowledged the enormity of the challenges facing the new government, including over a decade of sluggish economic growth and a significant public finance deficit. Despite these challenges, the government has prioritized economic growth as its national mission, aiming to achieve the highest sustained growth in the G7.
The UK economy demonstrated a recovery from its recent recession, achieving a 0.6% growth in the second quarter, according to the latest data from the Office for National Statistics (ONS). This follows a robust 0.7% growth in the first quarter, indicating a sustained upward trajectory after two consecutive quarters of contraction last year.
The services sector was a significant contributor to this growth, with particular strength observed in the IT industry, transport, and architecture sectors. These sectors experienced substantial increases, reflecting the broader resilience and adaptability of the UK’s service-oriented economy.
The new Labour government, which has committed to revitalizing the UK economy, views this growth as a significant boost. Finance Minister Rachel Reeves has set ambitious targets, including achieving the fastest per capita GDP growth among the Group of Seven advanced economies for two consecutive years. This goal is part of a broader strategy to address the long-standing challenges of low business investment and the economic instability exacerbated by the UK’s exit from the European Union.
These positive growth figures are particularly encouraging for the newly elected Labour government, which has emphasized economic growth as a central policy objective. During the election campaign, the Labour party highlighted the need to drive economic expansion and address the challenges inherited from the previous administration, including low growth and a significant public finance deficit.
However, despite this positive momentum, the UK economy still faces significant challenges. Since the onset of the COVID-19 pandemic, the UK’s economic growth has been relatively modest, with a cumulative growth of 2.3% compared to other major economies. This performance is only surpassed by Germany, which has faced severe economic pressures due to the reduction in Russian gas availability and subsequent increases in energy prices following the Ukraine conflict.
While the UK’s economic recovery is promising, it is set against a backdrop of broader economic challenges and comparative underperformance relative to other major economies. In fact, this recovery is significantly lower than inflation.
The UK economy has demonstrated resilience by achieving a 0.6% growth in the second quarter of 2024, aligning with economists’ forecasts. This growth follows a robust 0.7% increase in the first quarter, marking a significant rebound from the shallow recession experienced in the second half of 2023.
According to data released by the Office for National Statistics (ONS), the UK’s gross domestic product (GDP) remained stable in June, consistent with expectations from a Reuters poll among economists. Compared to the same month last year, GDP rose by 0.7%.
Suren Thiru, the director of economics at the Institute of Chartered Accountants in England and Wales, noted that while the current growth is encouraging, there are concerns that economic expansion in the second half of 2024 could slow. Factors contributing to this potential slowdown include persistently high interest rates, supply constraints, and slower wage growth. Despite the Bank of England’s recent interest rate cut from 5.25% to 5%, these headwinds are expected to limit output.
The service sector, particularly areas such as technology, scientific research, and legal services, has been a key driver of this growth. However, this positive performance was somewhat offset by declines in retail and reduced output in the television and film industry, which were impacted by the Screen Actors Guild strikes in the United States during 2023.
The new Labour government, which has committed to revitalizing the UK economy, views this growth as a significant boost. Finance Minister Rachel Reeves has set ambitious targets, including achieving the fastest per capita GDP growth among the Group of Seven advanced economies for two consecutive years. This goal is part of a broader strategy to address the long-standing challenges of low business investment and the economic instability exacerbated by the UK’s exit from the European Union.
The Bank of England has revised its annual growth forecast for 2024 upwards from 0.5% to 1.25%, driven by a stronger-than-expected start to the year. The bank anticipates a 0.7% growth rate for the second quarter. However, the outlook for the remainder of the year is less optimistic, with growth expected to slow to 0.4% in the third quarter and further to 0.2% in the last quarter, aligning with the underlying growth of the economy.
Since the onset of the COVID-19 pandemic, the UK economy has experienced modest growth, increasing by only 2.3% between the fourth quarter of 2019 and the second quarter of 2024. This performance is surpassed only by Germany among major advanced economies, which has faced significant challenges due to rising energy costs following Russia’s invasion of Ukraine.
Prime Minister Keir Starmer has set an ambitious target for the UK economy to achieve annual growth of 2.5%, a goal that has not been consistently met since the 2008 financial crisis. This target was emphasized during the election campaign leading up to the elections on 4 July. Finance Minister Rachel Reeves has formally set the goal for the UK to lead the Group of Seven Advanced Economies in GDP per capita growth for two consecutive years.
Despite these ambitions, recent data indicates that production per capita in the second quarter of 2024 was 0.1% lower than the previous year and 0.8% lower than pre-pandemic levels. Reeves acknowledged that the latest figures highlight the challenges facing the new government and reiterated the need for difficult decisions to strengthen economic fundamentals.
The growth of production per hour worked in the UK has been slow, a trend common in most advanced economies since the late 2000s. This has been exacerbated by domestic issues such as low business investment and the public’s decision to leave the European Union in 2016.
Retail sales in the UK increased less than expected in July, according to figures from the British statistical office. On a monthly basis, sales volumes rose by 0.5%, falling short of the expected 0.7% increase. On an annual basis, sales in July increased by 1.4%, matching economists’ predictions.
British economists have warned that economic growth may decline as high interest rates persist. Despite the Bank of England’s recent interest rate cut in August, high interest rates continue to slow down spending by businesses and consumers, negatively impacting economic growth.