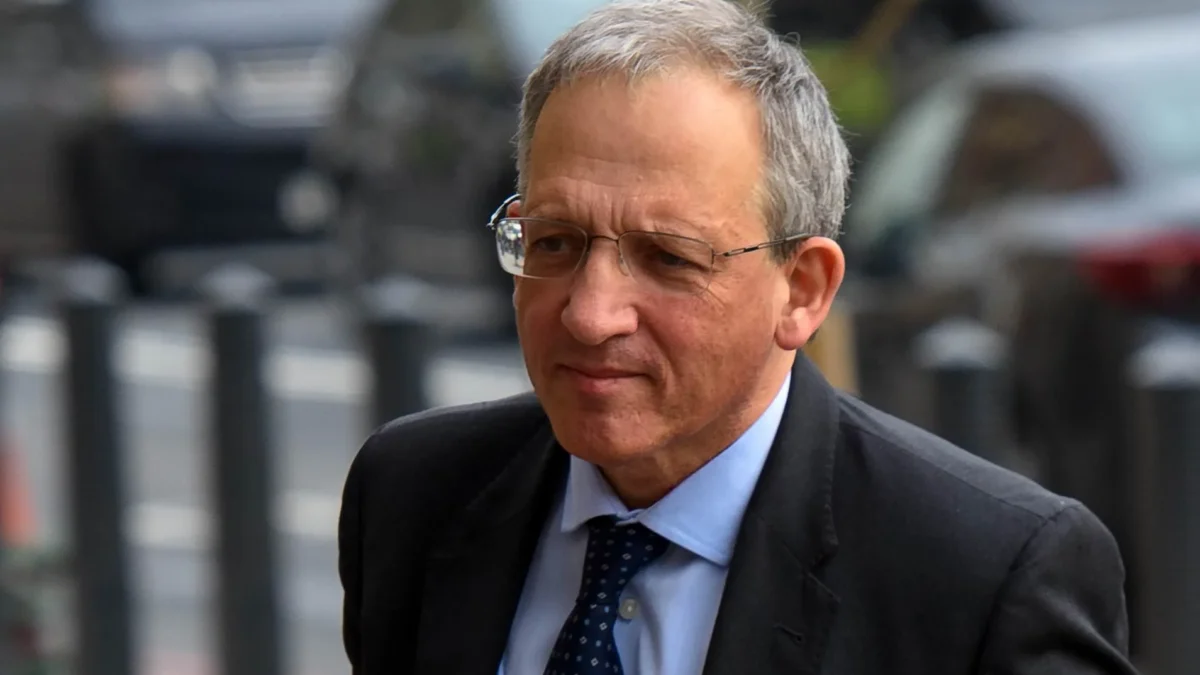
According to Jon Cunliffe, deputy governor of the Bank of England (BoE), there may be a need for a digital version of the British pound. This he indicated while discussing the collapse of FTX and whether the debacle should influence the decision to issue one.
He initially thought that there was no connection between the collapse of FTX and the central bank’s work on a central bank digital currency. He said the following at the Warwick Business School’s Gilmore Center Policy Forum Conference on DeFi and digital currencies:
“Over the past few days, I’ve gotten a few comments that the collapse of FTX shows that we need to go ahead and spend a digital pound of our own – and that FTX shows that we don’t need to.”
The comments are justified because FTX in particular is emblematic of these new technologies and the possibility that they can revolutionize financial services and the forms that money takes, said the vice governor.
Earlier this month, FTX filed for bankruptcy in the US after a liquidity crisis caused by an article by CoinDesk led to its collapse. Cunliffe said on Monday that crypto needed to be brought within the relevant policy frameworks in the UK to protect consumers, investors, financial stability and enable innovation. Earlier, he called for extending existing financial regulations to crypto.
Parliament is discussing the financial services and markets bill, which could eventually lead to regulation of crypto as financial instruments and UK regulators. The Bank of England plans to regulate major issuers of payment-focused crypto assets such as stablecoins.
It is reported that next year the central bank will launch a consultation on stablecoins that will look at the requirements for corporate structure, governance, accountability and transparency needed to meet the standards expected in other parts of the financial system. He said:
“The FTX example underlines how important these aspects are.”
“The BoE has also investigated the issue of a digital pound. The BoE’s work on a “digital native pound” is driven by trends in payments including the declining role of cash, and more generally in the increasing digitization of everyday life.”
“Our approach as regulators needs to be open – by which I mean we need to be willing to explore whether and if so, how the necessary level of certainty equivalent to that in conventional funding can be achieved. But we must also be determined that where that is not possible, we are not willing to see innovation at the expense of higher risk.”