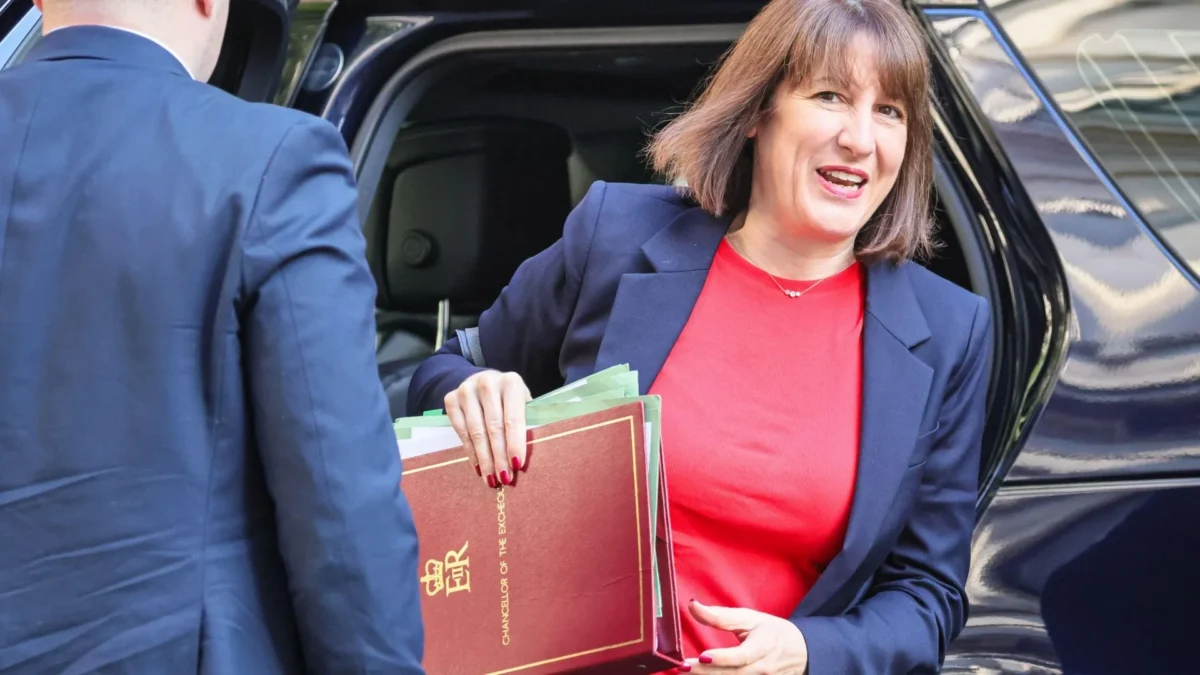
The UK economy has faced significant challenges in its recovery, and recent data has not been encouraging. Despite expectations of a 0.2% growth in September, the economy unexpectedly contracted by 0.1%, a figure that has left Finance Minister Rachel Reeves unsatisfied.
This contraction is part of a broader trend of economic stagnation. In September, both the industry and construction sectors experienced declines, while the service sector managed to maintain its output levels. For the third quarter, the economy saw a minimal growth of 0.1%, a sharp drop from the 0.5% growth recorded in the previous quarter.
The UK’s economic struggles are not new; the country endured a recession last year and has been one of the slower-recovering economies among developed nations. In fact, only Germany is performing worse among the developed economies.
In an effort to boost economic performance, the new Prime Minister, Keir Starmer, announced an ambitious economic growth target of 2.5% in July. This goal aims to position the UK as the leader in economic growth among G7 countries. However, achieving this target will be challenging given the current economic landscape.
The UK’s economic outlook is further complicated by various factors, including persistent inflationary pressures. As of August 2024, the Consumer Price Index (CPI) inflation remained steady at 2.2%, with core inflation rising to 3.6% due to high services sector prices and other domestic price pressures.
Additionally, the impact of Brexit continues to hinder UK-EU trade, with significant declines in both exports and imports since 2021. UK exports to the EU have fallen by 17%, and imports are down by 23% compared to pre-Brexit projections, largely due to new regulatory barriers and customs checks.
Despite these challenges, there are some positive signs. Market expectations of rate cuts have boosted economic growth, and lower financing costs are expected to continue supporting investment. The housing market has resumed growth, and interest rate cuts are anticipated to add further stimulus to the economy by the end of 2026.
The labour market, although loosening, remains relatively strong, with the unemployment rate at 4.1% in June and wage growth at 4.9% in the three months to July. However, this strong labour market also poses risks of increasing inflationary pressures, making the Bank of England’s task of managing growth and inflation particularly challenging.
There are indications that easing monetary policy and lower interest rates could stimulate growth in the coming months. The new government’s ambitious growth targets will require careful management of these economic factors to achieve the desired outcomes.