The UK government’s plans to invest £2.5 billion in the domestic steel industry has moved forward faster than expected. This was triggered by Donald Trump’s declaration regarding a 25% tax on all steel and aluminum imports into the United States which brought forth vigorous responses from the English political sphere. This is a testament to the Trump announcement’s shattering effects on the entire political system.
Business Secretary Jonathan Reynolds is preparing Plan Steel which he will turn into a Green Paper which is scheduled for publication on Sunday—but which will now be released weeks prior to schedule. Leaving the plan has stark ramifications for Whitehall as Trump’s trade policies are leaving panic in its wake. There is a clear need to act. The government is already in a deadlocked economy and has no choice but to urgently intervene to bolster British industrial capabilities.
Reynolds in his comments to the Observer stated that the United Kingdom was already slow in the development of their steel sector. Now compounded with Trump being back in office, there is severe competition to intervene and grow their steel sector. The president’s actions were indeed very damaging, but in a way when looked upon at the overall domestic and global economy, invokes some liberal thinking and strategising. Reynolds final comments on the Trump tariffs where very clear – it is another blockade to jump over, but at the same time makes the government’s need to formulate a steel policy of utmost importance.
Unlike the EU and Canada, which have threatened immediate retaliation if the tariffs take effect, the UK has so far refrained from adopting a confrontational stance. Each year, Britain exports approximately 209,000 tonnes of steel to the U.S. while importing just 16,000 tonnes, making the U.S. its second-largest market after the EU. Reynolds remains optimistic that ongoing negotiations with American officials could mitigate the economic damage, stressing that imposing such tariffs benefits neither side.
Gareth Stace, CEO of UK Steel, warned last week that U.S. protectionist measures could stifle British steel exports and further damage the UK’s already fragile trade balance. He pointed out that with the U.S. being Britain’s second-largest steel market, the proposed tariffs put more than £400 million in annual exports at risk.
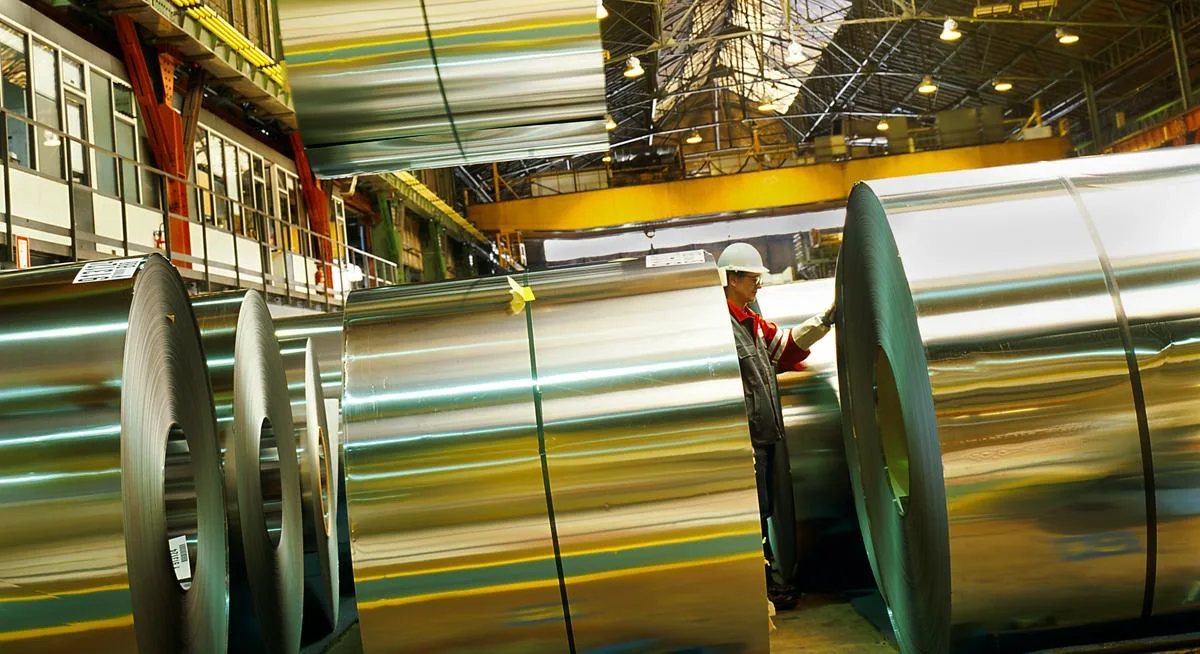
Part of the government’s investment strategy includes a dedicated £500 million package to support Tata Steel in partially funding new steel production in Port Talbot, South Wales. Originally outlined in an opposition manifesto, this broader £2.5 billion investment is aimed at revitalizing Britain’s struggling steel industry. Ministers are now working to determine how best to allocate these funds, prioritizing co-financing innovative projects with the private sector. The goal is to fortify the UK steel industry to the point where it can play a pivotal role in national infrastructure projects that underpin economic growth.
A recent announcement by Heathrow Airport provided a much-needed boost for British Steel, as the company pledged to use UK-manufactured steel in its largest-ever investment program. Heathrow indicated that domestic steel would also be prioritized should the long-debated third runway project receive official approval. The expansion plans include extensive use of British steel in key infrastructure projects, such as the construction of new terminal facilities and enhancements to Terminals 2 and 5.
During a parliamentary session last Wednesday, Liberal Democrat leader Ed Davey urged Prime Minister Keir Starmer to take a tougher stance against Trump’s trade policies. Davey argued that passively hoping for a favourable outcome was not a viable strategy and insisted that the UK must negotiate from a position of strength. Starmer responded by assuring that the government’s approach would be based on a comprehensive assessment of the potential consequences, though he refrained from outlining specific retaliatory measures.
The upcoming Plan Steel Green Paper will address several long-term issues plaguing the industry, including high energy costs, market volatility, and the impact of tariffs. It will also focus on sustainable solutions such as increasing metal recycling and transitioning to cleaner production methods to protect jobs and living standards in Britain’s steel-producing heartlands. A significant portion of the £2.5 billion investment is expected to fund the development of electric arc furnaces, which can heat steel to extreme temperatures without relying on fossil fuels.
Reynolds reaffirmed the government’s commitment to securing the industry’s future, stating that the UK steel sector remains a priority. He reiterated that the promises made during the election campaign are now being put into action, signalling a decisive shift in policy towards rebuilding Britain’s industrial base.